

If you’re asking what is a portfolio loan is, the simplest answer involves who keeps your mortgage. The originating lender retains the mortgage instead of selling it to another investor. That choice can create more flexible underwriting for borrowers with unusual financial situations.
| Key point | What it means |
| Basic definition | The lender originates the mortgage and keeps it on its balance sheet. |
| Main advantage | Underwriting can be more flexible than standard conforming guidelines. |
| Common users | Self-employed borrowers, investors, jumbo borrowers, and buyers of unusual properties. |
| Main drawback | Rates, fees, down payments, or reserve requirements may be higher. |
| Availability | Programs vary significantly among banks, credit unions, and other lenders. |
| U.S. context | Portfolio lending often serves situations that do not fit standard secondary-market rules. |
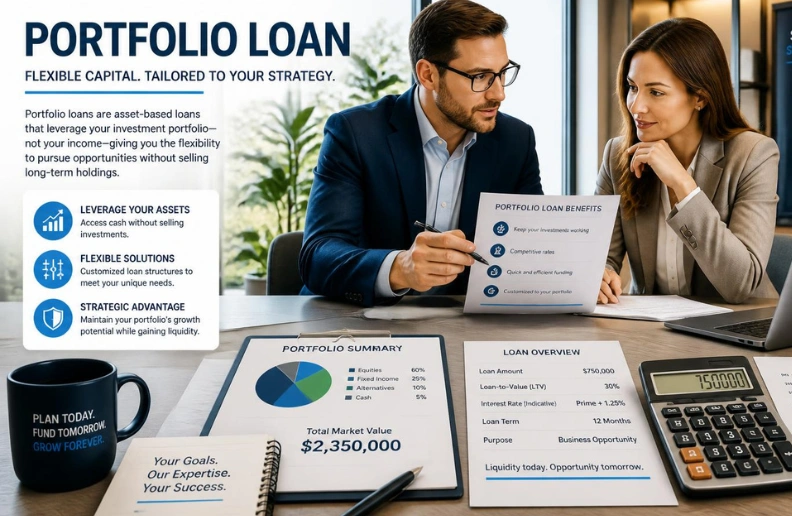
Direct answer: A portfolio loan is a mortgage that the originating lender keeps on its own balance sheet instead of selling it. Because the lender retains the credit risk, it can set more flexible underwriting rules. In exchange, borrowers may face higher rates, fees, down payments, or reserve requirements.
Key Takeaways
- Portfolio mortgages stay with the originating lender rather than being sold into the secondary mortgage market.
- Lenders can use their own underwriting standards, although borrowers must still show an ability to repay.
- These mortgages can suit self-employed borrowers, investors, unusual properties, and some jumbo financing situations.
- Compare total costs carefully because greater flexibility can come with higher pricing or stricter conditions.
What Is a Portfolio Loan and Why Does It Matter?
Most U.S. mortgage borrowers never think about what happens to their loan after closing. Many mortgages can be sold to investors or government-sponsored enterprises in the secondary market. Fannie Mae and Freddie Mac are major participants in that system.
What Is a Portfolio Loan follows a different path because the lender intends to hold the debt. The lender therefore accepts the ongoing credit risk attached to the mortgage. That arrangement gives the institution more control over its underwriting standards and loan structure.
The word “portfolio” describes where the mortgage is held after origination. It does not describe one universal interest rate, down payment, or repayment structure. Each participating lender can build products around its own risk policies.
How Do Portfolio Mortgages Work?
The application process can look familiar to anyone who has applied for a standard mortgage. You provide information about income, assets, debts, credit history, and the property. The lender then determines whether the transaction fits its internal requirements.
The difference appears most clearly during underwriting. A lender holding the mortgage can consider factors outside standardized agency guidelines. Strong reserves, substantial equity, or unusual income documentation might influence the lender’s decision.
Flexible underwriting does not mean automatic approval. The lender still risks losing money if the borrower defaults. It may compensate for added risk through pricing, equity requirements, cash reserves, or other conditions.
Portfolio Mortgage vs. Conventional Conforming Mortgage
Both options can finance residential real estate, but their underwriting systems differ. A conforming mortgage must meet requirements allowing purchase by Fannie Mae or Freddie Mac. A lender-held mortgage can instead follow the institution’s own approved standards.
| Feature | Portfolio mortgage | Conventional conforming mortgage |
| Loan ownership | Usually retained by the originating lender | May be sold into the secondary market |
| Underwriting | Based on lender-specific rules | Must satisfy applicable conforming standards |
| Income situations | May allow greater flexibility | Usually follows standardized documentation rules |
| Property eligibility | Can accommodate some unusual properties | Property must satisfy applicable program requirements |
| Pricing | Can cost more depending on risk | Often benefits from broader market competition |
| Availability | Varies widely by lender | Widely available from mortgage lenders |
A conventional mortgage may be less expensive when you qualify comfortably under standard guidelines. A lender-held option becomes more useful when a strong application misses a particular conventional requirement. Comparing both paths can reveal whether the added flexibility is worth its cost.
Who May Benefit From a Portfolio Mortgage?
Self-employed borrowers may be a good fit because their taxable income can look different from salaried income. Real estate investors can also encounter financing challenges as their holdings become more complex. Buyers of unusual or higher-priced properties may face similar issues.
These programs can also suit borrowers with substantial assets but irregular monthly income. A lender might consider strong reserves or equity alongside traditional income measures. The exact treatment depends on that institution’s underwriting policies.
Investors should still evaluate the property as carefully as the financing. BusInvesty’s guide to home inspections and real estate decisions explains how property condition can affect transaction risk. Financing flexibility cannot make a weak property investment financially sound.
What Requirements Should You Expect?
No single national qualification checklist covers every lender-held mortgage. Lenders generally review credit, income, assets, debts, reserves, property value, and requested loan size. One institution’s acceptable borrower may therefore fall outside another institution’s guidelines.
A lender may allow flexibility in one area while being stricter elsewhere. Irregular income could be acceptable when the borrower has significant liquid reserves. An unusual property might require more equity to reduce the llender’sexposure.
Self-employed applicants should keep business and personal financial records organized before applying. Understanding the difference between top-line receipts and broader income measures can also help. BusInvesty’s explanation of revenue versus sales provides useful background for business owners reviewing financial statements.
Rates, Fees, and Other Costs
Portfolio mortgage pricing is not standardized across the U.S. market. Rates can differ according to credit, equity, property type, documentation, loan size, and lender policies. Borrowers should not assume flexible underwriting means inexpensive financing.
Some lenders may charge more because they retain the credit risk themselves. Closing costs and other fees can also differ among offers. The total borrowing cost matters more than comparing advertised interest rates alone.
The CFPB recommends comparing standardized Loan Estimates from multiple mortgage lenders. These forms show expected rates, monthly payments, closing costs, and certain risky loan features. Comparing equivalent offers makes differences easier to identify.
Why the 2026 Conforming Loan Limit Matters
Loan size can influence whether standard conforming financing is available. For 2026, the baseline one-unit conforming limit is $832,750 in most U.S. counties. Higher limits apply in designated high-cost areas and certain U.S. jurisdictions.
A mortgage above the applicable conforming limit is considered a jumbo loan. Jumbo financing does not automatically mean the mortgage must remain with its original lender. Still, some banks choose to hold certain jumbo mortgages as portfolio assets.
Borrowers should check the limit applying to their property’s county. They should then compare jumbo programs alongside any lender-held alternatives. Loan amount alone should not determine which mortgage structure you choose.
Portfolio Lending for Real Estate Investors
Real estate investors often have financial profiles that become complicated after several property purchases. Rental income, existing mortgages, reserves, and property types can all affect underwriting. A lender using internal guidelines may have more room to evaluate that complete picture.
Investors should calculate operating economics before focusing on financing approval. Property income must support expenses, vacancies, repairs, taxes, insurance, and debt payments. Flexible financing cannot replace sound cash-flow analysis.
This principle also matters for entrepreneurs buying property connected with an operating business. BusInvesty’s laundromat startup guide discusses financing among the major planning decisions for that business model. BusInvesty’s car wash franchise guide also shows why real estate costs belong inside the broader investment calculation.
Is a Portfolio Mortgage the Same as a Non-QM Mortgage?
No single label should be assumed from the word “portfolio.” Portfolio status describes the lender’s decision to hold the mortgage. Qualified Mortgage status concerns federal ability-to-repay standards and other regulatory requirements.
Some mortgages held in portfolio can qualify under Qualified Mortgage rules. CFPB regulations even include provisions that apply to certain Qualified Mortgages held by eligible creditors. So a lender-held mortgage isn’t automatically a non-QM product.
Ask the lender how the specific mortgage is classified before signing anything. You should also understand whether payments can change, whether penalties apply, and how the loan amortizes. Those details matter more than marketing labels.
How to Compare Portfolio Loan Offers
Start by asking several banks, credit unions, mortgage companies, or brokers about available programs. Explain your financial situation and the property accurately from the beginning. Different institutions can have substantially different appetites for the same transaction.
Request comparable Loan Estimates whenever the mortgage type qualifies for that disclosure. The CFPB recommends comparing multiple offers rather than evaluating a single lender. Look closely at rates, lender fees, cash required, monthly payments, and adjustable features.
You should also ask whether the loan includes a prepayment penalty or balloon feature. Confirm whether the interest rate stays fixed throughout the term. Ask what circumstances could change your payment before committing.
Finally, compare the proposed mortgage against standard conventional, government-backed, and jumbo options you can access. Greater underwriting flexibility matters only when it solves a real qualification problem. Paying extra for flexibility you do not need can increase long-term borrowing costs.
Should You Consider One?
This financing structure may be worth considering when conventional underwriting does not reflect your full financial strength. It can also help with properties that fall outside common agency requirements. The value depends on the specific terms each lender offers. offers
Borrowers who easily qualify for competitive conventional financing should compare that route first. Lower costs could outweigh the customized features of a lender-held mortgage. The decision should reflect both approval chances and the total cost of ownership.
Your next step is to request comparable written offers from several lenders. Review the Loan Estimates against your budget and expected ownership period. Choose financing based on documented costs, risks, and repayment terms, not the product name.
Frequently Asked Questions
What is a portfolio loan?
A portfolio loan is a mortgage the originating lender keeps as an asset instead of immediately selling it. Retaining the loan allows the lender to apply its own underwriting standards. Those standards can offer flexibility, although pricing and requirements vary by institution.
Are portfolio loans harder to qualify for?
They are not automatically harder or easier to qualify for. A lender may relax one requirement while demanding stronger reserves or equity elsewhere. Qualification depends on your finances, property, requested amount, and the institution’s policies.
Do portfolio mortgages have higher interest rates?
They can have higher borrowing costs than standard conforming mortgages. The lender retains more risk and may price that risk into the mortgage. Always compare current Loan Estimates instead of relying on general rate assumptions.
Can real estate investors use portfolio mortgages?
Yes, some lenders design these products for investors and complex real estate situations. Availability and underwriting standards still differ substantially among institutions. Investors should compare financing costs against expected property cash flow before borrowing.
Can a lender sell a portfolio mortgage later?
Keeping a mortgage in portfolio does not always guarantee the original lender will retain ownership. Certain loans can later be transferred or sold, depending on their structure and applicable rules. Review your loan documents rather than assuming servicing or ownership can never change.
Is a portfolio mortgage always a non-QM loan?
No, portfolio status and Qualified Mortgage status describe different characteristics. Certain Qualified Mortgages can be held in portfolio under federal rules. Ask your lender about the classification and protections applying to your specific mortgage.
