

If your business accepts credit or debit cards, several systems work behind each payment. One important part is the merchant account used during payment processing. Understanding its role helps you compare providers, fees, and payment setups with more confidence.
Direct answer: A merchant account is a specialized financial account used to process card and electronic payments. It temporarily receives funds from approved customer transactions before settlement to your business bank account. Businesses may have dedicated accounts or access this function through payment service providers.
Merchant Account at a Glance
| Topic | What It Means |
|---|---|
| Main purpose | Supports acceptance and settlement of electronic payments |
| Common payments | Credit cards, debit cards, and other supported electronic payments |
| Where money ends up | Your regular business bank account |
| Key parties | Merchant, processor, acquiring bank, card network, and issuing bank |
| Dedicated account required? | Not always; payment facilitators can provide access through shared arrangements |
| Common costs | Processing, monthly, chargeback, equipment, or other provider fees |
| Best for | Businesses accepting card or electronic customer payments |
What Is a Merchant Account?
A merchant account is a specialized account that helps businesses accept electronic payments from customers. It forms part of the infrastructure behind credit and debit card transactions. Funds generally pass through the payment system before reaching the company’s regular bank account.
This account is different from the checking account used for normal business expenses. You generally don’t use it to pay rent, payroll, or everyday bills. Its main purpose is payment authorization, processing, settlement, and moving customer funds.
For business owners, the distinction matters because payment processing involves several companies and financial institutions. Customers usually see a simple card reader or online checkout page. Behind that interface, banks, networks, processors, and payment technology exchange transaction information.
How Does a Merchant Account Work?
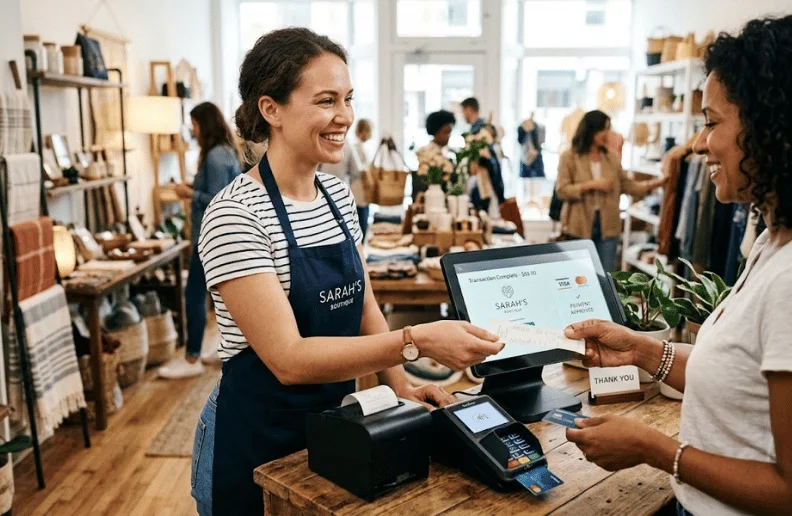
A card transaction starts when a customer presents payment at a store or online checkout. Payment information travels through the processor and the relevant card network for authorization. The customer’s issuing bank then approves or declines the transaction.
An approval does not mean the money instantly appears in your checking account. Approved transactions still need to clear and settle. The acquiring side of the payment system handles this process before your provider sends eligible funds to you.
A simplified payment flow looks like this:
- The customer pays with a credit or debit card.
- The payment system securely sends the transaction for authorization.
- The card issuer approves or declines the payment.
- Approved transactions proceed through clearing and settlement.
- Funds move through the merchant payment arrangement.
- The provider deposits eligible proceeds into your business bank account.
Payment and deposit timing varies by provider and account arrangement. Some providers offer faster funding options for eligible businesses. Others use standard settlement schedules that can take longer.
Merchant Account vs. Business Bank Account
These two accounts serve different functions, even though both connect to your company’s money. A business checking account manages your operating funds after they become available. The payment account supports card transaction processing before settlement reaches that checking account.
| Feature | Merchant Payment Account | Business Bank Account |
|---|---|---|
| Accepts card transactions | Yes, as part of processing | Not by itself |
| Holds operating cash | Generally no | Yes |
| Used for payroll and bills | No | Yes |
| Connected with payment processing | Yes | Receives settled proceeds |
| Main purpose | Card payment settlement | Everyday business banking |
Think about the distinction from an operational perspective. Your checking account is where your company manages available money. The payment arrangement is part of the system that helps card revenue reach that account.
Merchant Account vs. Payment Gateway
A payment gateway performs a different function from the financial account behind settlement. The gateway securely captures and transmits payment information during an electronic transaction. It is especially relevant when customers enter payment information on a website or application.
The financial account handles the settlement side rather than acting as the checkout technology. Both components can operate within one provider’s platform. That integration can make them appear like one service to a business owner.
This distinction matters when comparing payment companies. One quote might bundle gateway, processing, and settlement services into a single price. Another provider may list these components and their fees separately.
Merchant Account vs. Payment Processor
A payment processor handles transaction communications among businesses, banks, and card networks. It helps route authorization information and supports clearing and settlement. By comparison, the financial account is associated with receiving or holding transaction funds during settlement.
Modern payment companies often bundle these functions together. A business owner may therefore never manage each component separately. You should still understand each role before comparing prices or contracts.
Knowing the difference can also make provider statements easier to understand. Ask which company processes transactions and which institution handles acquiring services. Then confirm how and when your sales proceeds reach your bank.
Do You Need a Merchant Account to Accept Credit Cards?
Your business needs access to the merchant acquiring system if it accepts card payments. That does not always mean opening a standalone account directly with an acquiring bank. Many modern payment service providers handle the underlying arrangement for their customers.
A dedicated setup is underwritten for each business. Providers may review your industry, sales volume, transaction patterns, chargeback exposure, and operating history. Approval requirements vary because providers assess businesses differently.
Payment facilitators offer another approach for many small businesses. They can onboard merchants under a broader payment arrangement instead of requiring every seller to establish a separate direct relationship. This model often simplifies setup for smaller or newer companies.
Dedicated Merchant Accounts vs. Payment Service Providers
A dedicated account can suit established companies with substantial or specialized payment needs. These arrangements may offer customized pricing, underwriting, support, or processing terms. Businesses with higher transaction volumes may value that additional control.
A payment service provider can be easier for businesses seeking simpler onboarding. The provider combines payment functions and manages much of the underlying infrastructure. This approach is common among small businesses, online sellers, and companies wanting a straightforward setup.
Neither model automatically fits every company. Your sales volume, industry, average transaction size, refund patterns, and payment channels can affect the choice. Contract terms and total costs deserve as much attention as the advertised transaction rate.
What Fees Should U.S. Businesses Expect?
Payment acceptance costs rarely include a single universal fee. Providers use different pricing models, service packages, and contract structures. Your final cost can also depend on transaction type, card type, sales channel, and business risk.
Common charges can include the following.
- Per-transaction processing fees
- Monthly account or service fees
- Gateway fees
- Chargeback or dispute fees
- Equipment or terminal costs
- PCI-related fees or services
- Batch fees
- Setup fees
- Early termination fees under some contracts
Don’t compare providers using one percentage alone. Request a complete fee schedule and review the contract terms. A low advertised rate may not represent the total cost of accepting payments.
You should also examine how card-present and card-not-present transactions are priced. Online transactions can have different risk characteristics from in-person sales. Your actual sales mix can therefore affect your processing expenses.
What Is Underwriting and Why Does It Matter?
Payment providers take financial risk when they process transactions for a business. Customers can dispute transactions after a sale, and merchants can issue refunds. Fraud, business closure, or unusually high chargebacks can create additional exposure.
Underwriting helps a provider evaluate that risk before approving a dedicated payment relationship. The provider may request company information, bank details, expected sales volume, and ownership information. Certain industries or business models can face additional review.
Accurate application information can reduce problems later. Large differences between stated and actual transaction patterns may trigger reviews or funding controls. Businesses should update providers when major operational changes affect payment activity.
What Are Chargebacks and Reserves?
A chargeback occurs when a cardholder disputes a transaction through the card issuer. The Consumer Financial Protection Bureau explains that cardholders have 60 calendar days after a charge appears on their statement to send a written billing error notice. The dispute process can result in the merchant losing money while the case is reviewed. Businesses may also face a separate chargeback fee from their provider.
Good records can help when responding to disputes. Keep receipts, delivery information, customer communications, refund records, and relevant transaction details. Clear billing descriptions can also reduce confusion that sometimes leads to disputes.
Some providers may establish a reserve for certain businesses or risk profiles. A reserve means the provider may hold part of the processed funds under defined terms. Review reserve conditions carefully because they can affect working cash flow.
How to Choose a Merchant Account Provider
Start with your actual payment needs instead of comparing headline rates. A restaurant, subscription company, professional service, and e-commerce store can have different transaction patterns. Your provider should support the ways customers genuinely pay your business.
Compare these areas before signing.
- Complete processing and account fees
- Contract length and cancellation terms
- Funding and settlement schedules
- Chargeback policies and fees
- Reserve or hold provisions
- Supported payment channels
- Point-of-sale and e-commerce integrations
- Customer support availability
- Security and fraud-management tools
- Reporting and reconciliation features
Read the agreement before committing to a long-term arrangement. Ask questions about any fee, reserve, or cancellation clause you don’t understand. Written terms matter more than a salesperson’s informal explanation.
A Simple Example
Suppose a customer buys a $100 product from a U.S. online store using a credit card. The checkout system securely sends the transaction through the payment infrastructure. The customer’s card issuer then decides whether to approve the purchase.
After approval, the transaction proceeds through clearing and settlement. The payment provider calculates applicable fees according to the merchant’s agreement. The provider then deposits the remaining eligible proceeds into the business’s designated bank account.
This example shows why the customer’s payment doesn’t go straight into a checking account. Several systems process and settle the transaction. The exact timing and charges depend on the provider and agreement.
Frequently Asked Questions
What is a merchant account used for?
A merchant account supports accepting and settling electronic customer payments. It connects a business with the financial infrastructure used for card transactions. Settled proceeds ultimately move into the business’s designated bank account.
Can I accept credit cards without opening my own dedicated account?
Yes, many businesses use payment service providers instead of opening a dedicated account directly. These providers give merchants access to payment processing through their broader acquiring arrangement. The exact structure depends on the provider and service.
Is a merchant account the same as a payment gateway?
No, they serve different functions. A payment gateway securely transmits payment information during a transaction. A merchant account handles processing and settlement of approved funds.
How long does merchant account settlement take?
Settlement speed depends on the provider, transaction, bank, and account terms. Some services offer accelerated funding for eligible merchants. Standard deposits may take longer, so confirm the provider’s written funding schedule.
What information is needed to apply?
Requirements vary by payment provider and acquiring institution. Businesses may need company details, ownership information, bank information, and estimated processing volumes. Providers can request additional documents during underwriting.
Are merchant accounts only for online businesses?
No, businesses can use payment processing for online and in-person transactions. Retail stores, restaurants, service companies, and ecommerce businesses can all accept card payments. The hardware and payment technology may differ between sales channels.
The Bottom Line for U.S. Business Owners
Understanding payment infrastructure helps you make better decisions about accepting customer cards. Focus on total costs, settlement timing, contract terms, disputes, and provider support. Those details can affect both daily operations and cash flow.
You also don’t need to become a payments expert before accepting your first card. You do need to understand what your provider supplies and what it charges. Compare written terms carefully before choosing a service for your business.
For more practical business and finance explanations, continue exploring BusInvesty’s guides, such as how online banking works. Use each guide to understand the financial tools behind running a company. Better information makes provider comparisons easier and helps you ask more useful questions.
