

Starting a company involves more than filing paperwork with your state. You need a viable offer, a legal structure, tax registration, and a workable financial plan. This guide explains how to build a business in the United States, from validating your idea to launch.
Direct answer: To create a business in the U.S., validate demand, write a simple plan, and choose a legal structure. Register the company, obtain tax IDs, and secure required licenses. Then separate business finances, arrange insurance, build reliable records, and launch your offer.
| Key question | Practical answer |
|---|---|
| Where should you start? | Confirm that real customers need your product or service. |
| Do you need a business plan? | Yes, although a simple operating plan can work for many small businesses. |
| Which structure can you choose? | Common choices include sole proprietorships, partnerships, LLCs, and corporations. |
| Where do you register? | Registration requirements usually depend on your state, location, and entity type. |
| What is an EIN? | A federal tax identification number issued by the IRS. |
| Does an EIN cost money? | The IRS issues EINs directly at no charge. |
| Do you need licenses? | Requirements depend on your industry, state, county, and city. |
| Should you open business banking? | Separate banking simplifies bookkeeping and keeps business transactions organized. |
| Do U.S. companies file BOI reports in 2026? | Domestic U.S. companies are currently exempt under FinCEN’s final 2026 rule. |
| What comes after registration? | Set up accounting, insurance, operations, marketing, and a clear sales process. |
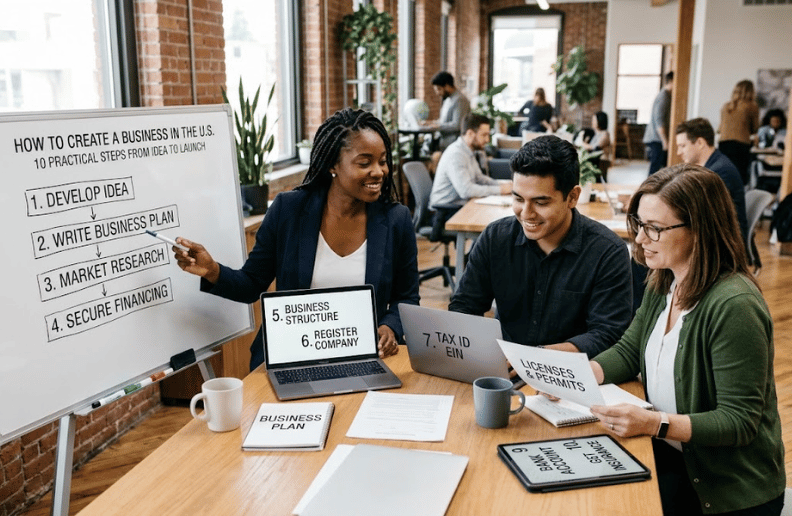
How to Create a Business in 10 Steps
The process becomes easier when you follow a clear sequence. Your state and industry may add extra requirements. Use these ten steps as your starting framework.
- Validate your business idea. Define the problem you solve and the customer who has that problem. Test whether buyers will pay before spending heavily.
- Write a practical business plan. Describe your offer, customers, competitors, pricing, costs, sales channels, and financial needs. Keep the plan useful rather than unnecessarily long.
- Choose your business location. Your location can affect taxes, zoning, licenses, and registration duties. Online companies may also have obligations in the places where they operate.
- Choose a legal structure. Compare sole proprietorships, partnerships, LLCs, and corporations. Consider liability, taxes, ownership, administration, and future funding.
- Choose and check your business name. Search your state’s business database before filing. You should also review trademark and domain availability.
- Register the business. File the required formation documents with the appropriate state agency. Filing rules and fees vary by state.
- Obtain federal and state tax IDs. Apply for an EIN when your business needs one. Complete state tax registrations when applicable.
- Get required licenses and permits. Requirements can come from federal, state, county, or city agencies. Confirm them before serving customers.
- Open business banking and set up accounting. Keep company transactions separate from personal spending. Build a recordkeeping system before activity becomes difficult to track.
- Protect and launch the business. Review insurance, contracts, payment systems, marketing, and operating procedures. Then start selling and measure how customers respond.
1. Validate the Idea Before Spending on Formation
A legal entity can’t save a product customers don’t want. Start by defining a specific customer and a clear problem. Then test whether your proposed solution produces genuine interest.
Speak with potential buyers and study existing alternatives. Compare prices, reviews, complaints, and common customer frustrations. BusInvesty’s guide to identifying market gaps offers a useful framework for this stage.
Validation can also start with a small paid offer. A freelancer might sell one defined service before building an agency. A product founder could collect preorders or test a limited batch.
2. Build a Simple Business Plan and Startup Budget
Your plan should explain how the company will make money. Define your product, target market, pricing, sales method, costs, and expected cash needs. The goal is better decisions, not impressive formatting.
Estimate both startup expenses and recurring monthly costs. Include equipment, software, inventory, professional services, advertising, insurance, and working capital. Add a buffer because early revenue can arrive slower than expected.
Funding may come from personal savings, investors, loans, or other sources. USAGov notes that federal grants generally do not fund ordinary business startups. Funding choices should match your risk tolerance and expected cash flow.
3. Choose the Right U.S. Business Structure
Your business structure affects taxation, administration, ownership, and legal exposure. Common options include sole proprietorships, partnerships, corporations, S corporations, and limited liability companies. The IRS recognizes different tax and filing rules for these structures.
A sole proprietorship can be straightforward for one owner. An LLC can legally separate the company from its owners. Corporations can fit businesses expecting outside shareholders or more complex ownership.
Do not choose an entity because it is popular online. Consider your state, ownership plans, tax situation, liability risks, and financing strategy. Complex situations deserve advice from qualified legal or tax professionals.
4. Register Your Name and Business With the State
Check whether your preferred name is available before building your brand around it. State naming rules can restrict duplicate or misleading names. Trademark issues are separate from state entity registration.
Businesses forming LLCs, corporations, or similar legal entities usually register with a state agency. The exact documents and fees vary by state. Some businesses may also need local registrations or assumed-name filings.
Your chosen location matters throughout this process. SBA guidance explains that location can determine zoning rules, taxes, and regulations. Research these requirements before signing a long lease.
5. Get an EIN in the Correct Order
An Employer Identification Number is a federal tax identification number. Partnerships, corporations, LLCs, employers, and several other entity types commonly need one. Banks and licensing authorities may also request an EIN.
As of 2026, the IRS says it issues EINs at no charge through its own application. If you form a legal entity, register it with your state before requesting the EIN. The IRS specifically instructs new legal entities to complete state formation first.
Avoid companies charging unnecessary fees for a basic IRS application. Third-party services can add convenience, but they don’t issue the EIN themselves. Keep your confirmation documentation with your permanent business records.
6. Check Licenses, Permits, and Current Federal Rules
Business licenses depend heavily on what you do and where you operate. A restaurant faces different requirements from a marketing consultant. Local zoning or home-occupation rules can also affect home-based businesses.
Industry-specific research matters because general startup checklists cannot cover every regulation. BusInvesty’s guides on starting an ATM business and a laundromat business show how requirements vary by industry.
One federal requirement has changed significantly. FinCEN finalized a rule on August 11, 2026, exempting U.S. companies from federal BOI reporting. Certain foreign entities registered in the United States can still have reporting duties.
7. Separate Business Money and Personal Money
Open a dedicated business account once your company is ready for financial activity. Separation creates cleaner records and makes tax preparation easier. It also gives you a clearer picture of your business’s actual performance.
Compare business bank accounts for an LLC based on your company’s expected transactions. Review monthly fees, cash deposits, ACH transfers, wires, branch access, software connections, and account minimums. A free monthly plan may still charge for specific transactions.
Set up bookkeeping at the same time. Categorize income and expenses consistently from the first transaction. Fixing months of mixed records later can consume unnecessary time and money.
8. Understand Taxes and Recordkeeping
Federal tax obligations depend partly on your entity and business activities. State and local taxes can create additional responsibilities. Sales tax rules also vary by location and what you sell.
The IRS recommends choosing a tax year and maintaining records needed for federal filings. Employers have additional payroll and employment-document responsibilities. State tax agencies may require separate registration.
Good records also make future financing or a sale easier. BusInvesty’s U.S. business-sale guide explains how buyers examine financial and operating documentation. Building those habits early can improve future decision-making.
9. Protect the Business With Insurance and Agreements
Insurance needs depend on the risks your company faces. General liability, professional liability, property coverage, commercial auto, cyber insurance, or workers’ compensation may be relevant. Requirements can also differ by state and profession.
Contracts deserve similar attention. Put important customer, vendor, partner, and contractor arrangements in writing. Clear terms can reduce disputes about payment, deadlines, ownership, and responsibilities.
Do not buy insurance based only on the cheapest premium. Compare exclusions, deductibles, limits, and the activities covered. Your policy should match the business you actually operate.
10. Prepare for Your First Customers
A registered company still needs a repeatable way to attract buyers. Choose one or two marketing channels that match your audience. Measure leads, conversions, acquisition costs, and repeat sales.
Prepare your payment process before launching. Decide how customers will pay, when invoices become due, and how refunds work. Test your website, forms, emails, checkout process, and customer support flow.
Start small enough to learn quickly. Customer behavior will expose assumptions planning can’t reveal. Improve the offer with real sales evidence, not guesses.
How Much Does It Cost to Create a Business?
No single national startup cost exists. State filing fees, licenses, insurance, inventory, equipment, rent, and professional services vary widely. A home-based service company may require far less capital than a physical retail business.
Separate mandatory costs from optional spending. Registration or licensing may be necessary, while expensive branding may be postponed. Spend early money on activities that reduce risk or help generate revenue.
Create three budget categories before launch. Track one-time setup costs, recurring fixed costs, and costs that rise with sales. This approach makes your cash needs easier to understand.
Common Mistakes New Business Owners Should Avoid
Many founders register an LLC before confirming customer demand. Others mix personal and business spending or overlook local permits. These mistakes can create costs before the company has proven its model.
Another common error is choosing a structure without understanding its consequences. Filing an entity is only one part of running it correctly. Tax filings, annual reports, licenses, records, and insurance can continue after formation.
Avoid assuming every online checklist applies equally nationwide. State laws and local requirements can change the process. Verify key requirements with official agencies in your area.
Frequently Asked Questions
How do I legally start a business in the United States?
Start by validating the idea and selecting an appropriate legal structure. Register the entity when required, obtain tax IDs, and secure applicable licenses. Then set up banking, recordkeeping, insurance, and ongoing compliance procedures.
Do I need an LLC to start a business?
No federal rule requires every new business to become an LLC. Some owners operate as sole proprietors, while others choose partnerships or corporations. Your best choice depends on liability, ownership, taxation, and future plans.
Can I start a business without an EIN?
Some sole proprietors may not need an EIN for federal tax purposes. Businesses with employees and several entity types generally do need one. The IRS also allows some businesses to request one for banking or state purposes.
How long does creating a business take?
The timeline depends on your state, entity type, licenses, and operating requirements. Some steps can happen quickly, while approvals or industry permits can take longer. Do not promise customers a launch date until critical approvals are confirmed.
Does every U.S. LLC need to file a BOI report in 2026?
No. FinCEN’s August 2026 final rule exempts entities created in the United States from BOI reporting. Certain foreign companies registered to conduct U.S. business can remain subject to the rule.
Turn Your Business Idea Into a Real Operating Company
A strong launch starts before the registration forms. Confirm demand, understand your numbers, and choose a structure that supports your goals. Then complete the legal and financial setup in the right order.
Treat compliance as an operating system, not a one-time task. Keep licenses, tax records, insurance, contracts, and financial information up to date. Review official state and federal guidance whenever your business changes.
Once the foundation is ready, focus on customers. Start selling, track what works, and improve the business from real evidence. A simple business that earns repeat customers is more valuable than a complicated plan that never launches.
